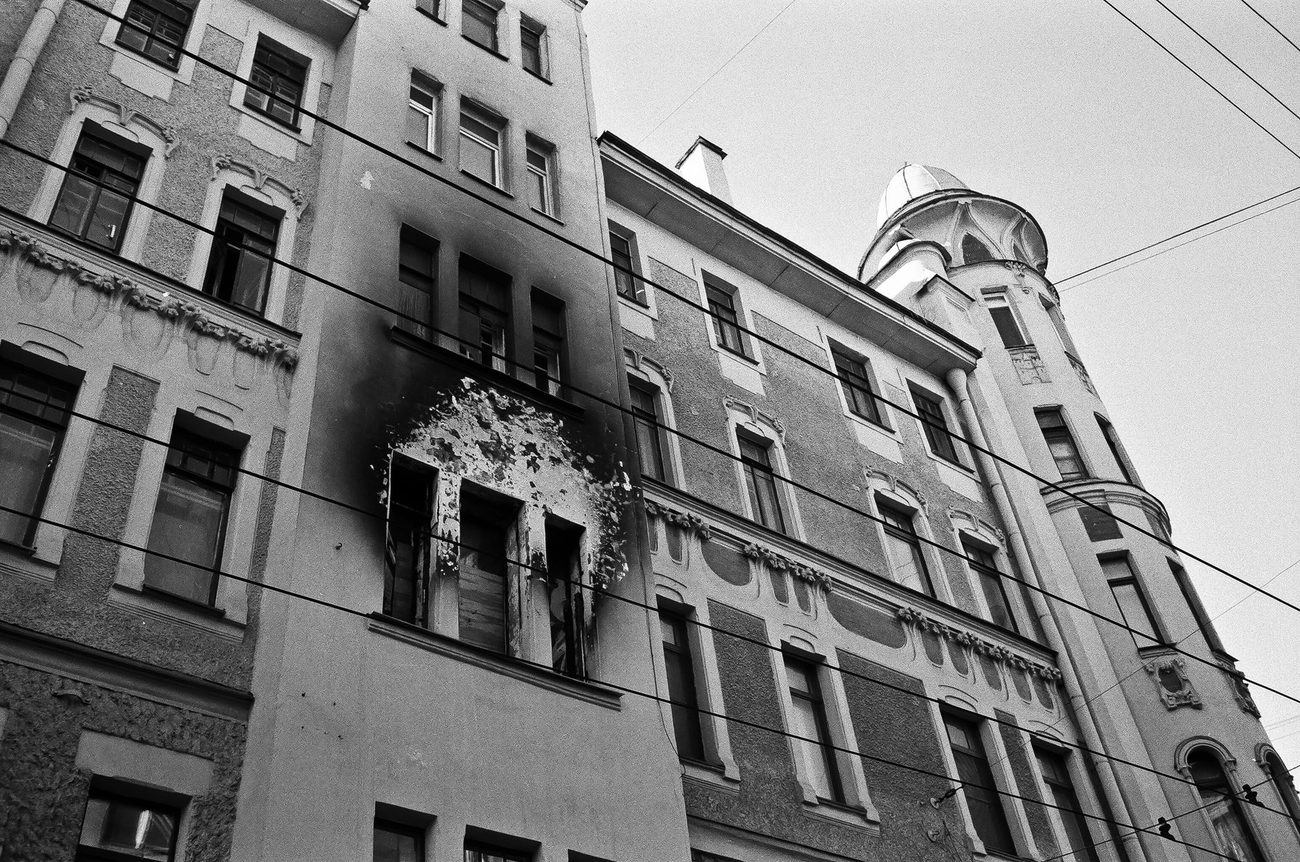
The smoke alarm in the stairwell went off at about 7 p.m. on a weeknight in March 2024. By the time Sam and I got Olive into her carrier and down three flights, the hallway on the first floor smelled like burned oil and two fire trucks were idling outside our building. A pan on the stove in a unit two floors below us had caught fire. Our neighbor was okay, thank goodness, and the fire department had it out in minutes. But their kitchen was a mess, and the water and smoke damage made it clear they'd be out of their apartment for a while.
Standing on the sidewalk in my slippers, I realized I had no idea what would happen if that had been our kitchen. We did not have renters insurance. Within a week, we did.
I'm not an insurance expert and this isn't advice about what anyone else should buy. It's just our story and how we thought it through.
What I assumed before (and why it was wrong)
For years, I'd lived with a vague belief that the landlord's insurance covered "the building" and therefore somehow covered me. After the fire, I asked our landlord directly. His answer was polite and clear: his policy covers the structure, not our stuff, and not us if we cause damage to someone else's unit.
That was the part that got my attention. If a fire started in our galley kitchen and spread smoke or water downstairs, who pays for that? Reading up on it, I learned that's where the liability part of a renters policy comes in.
Figuring out how much our stuff was worth
Our first instinct was "we don't own much." Then we actually walked around the apartment with a notepad. I'd recommend doing this even if you never buy a policy; it was eye-opening.
- Two laptops (mine is also my work machine)
- The bed, the couch, a dresser, the kitchen table and chairs
- Clothes and shoes for two people, including winter coats
- Kitchen stuff: pots, knives, the slow cooker, small appliances
- Books, a bike, a TV, and one very nice cast-iron pan
When we added up roughly what it would cost to replace everything new, not what we'd paid for it secondhand, it came out much higher than either of us expected. We also took a slow video of every room on my phone and saved it to cloud storage, which took ten minutes and is the easiest thing in this whole post.
What we ended up with
We got quotes from a few insurers and chose a basic policy. Here's what it looks like:
| Item | Ours |
|---|---|
| Monthly cost | $15 ($180 a year) |
| Personal property coverage | $30,000 |
| Liability coverage | $100,000 |
| Deductible | $500 |
We split it the way we split all our bills, proportionally to income: I pay 45%, Sam pays 55%. That works out to under $7 a month for my share.
A few things we noticed while shopping
- The deductible changed the price. A higher deductible lowered the monthly cost. We picked $500 because we could cover it from savings without panicking.
- Replacement cost vs. actual cash value. These pay out differently. I read the definitions twice and asked the agent to explain them, which I'd recommend over guessing.
- Both names on the policy. Since we're not married, we made sure both of us and our belongings were covered. Policies handle unmarried partners differently, so it's worth asking specifically.
- Read the exclusions. There were things it didn't cover. Knowing that up front is better than learning it after a bad day.
Has it been worth it?
We've never filed a claim, which is exactly how I'd like to keep it. So in strictly financial terms, we've paid about $285 so far for nothing tangible.
But I think about that night in March more often than I'd like. Our neighbor's kitchen was gutted and they were in a hotel for weeks. Fires in old buildings travel through walls, smoke gets into everything, and water from putting out a fire on one floor goes right through the ceiling of the next.
For us, the decision came down to this: we couldn't afford to replace our whole apartment's worth of stuff out of pocket, and we definitely couldn't afford to be on the hook for damage to someone else's home. Fifteen dollars a month for that peace of mind felt reasonable for our situation.
We also bought a small fire extinguisher for the kitchen that same week. It hangs on a removable hook next to the stove. Olive, for the record, has been suspicious of the stairwell ever since.